

Rear End Collision
$2,300,000
Insurer offered$85,000
Spinal cord injury after a rear end crash. The insurer offered $85,000.
Serving New Mexico
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
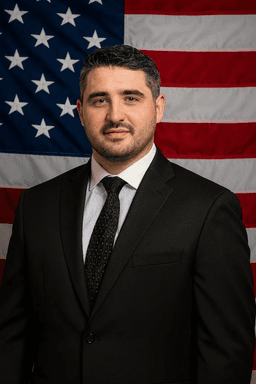 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in New Mexico.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In New Mexico, the first number the other driver's insurer puts on the table is rarely worth accepting. It comes before your treatment is finished, it assumes you have not checked the policy limits or your own coverage, and the release ends the claim permanently. Top USA Law reviews any New Mexico offer for free and tells you honestly whether it is fair. Call (877) 411-5291.
The first offer exists to close your file while the injury is still unknown, because an undiagnosed claim is the cheapest one to settle. A week after a crash on Paseo del Norte or Interstate 25, you know your back hurts and you missed some work. You do not know whether the pain is a strain or a disc injury, and neither does the adjuster. The offer is priced for that uncertainty in the insurer's favor: a small check, a friendly voice and a release that closes the claim before an MRI can change the picture.
In New Mexico nothing pays your bills in the background while you wait. There is no no fault benefit, so the check can look like the only money on the way as hospital statements arrive. It is not: the liability policy of the driver who hit you owes the full value of your injury, and behind it may stand your own uninsured or underinsured motorist coverage, which New Mexico insurers must offer with every policy. A release signed early can waive every layer at once.
Find out your diagnosis, your total losses, the limits on every policy, the liens on the recovery and whether fault is disputed.
It closes the claim against both the driver and the insurer for every injury, known or not. If the strain becomes a surgery next year, the release still holds. No adjuster's deadline binds you; the only hard date is the three year limit to file suit under NMSA 37-1-8 and the notice terms in your own policy.
Be polite, decline the recorded statement and the open ended medical authorization, keep every appointment and let a lawyer answer in writing. The other driver's insurer is entitled to nothing from you beyond your name, your carrier and the report number. Do not describe how you feel, do not guess at your own fault, and do not sign an authorization reaching your whole medical history, since old records become the argument that your pain predates the crash. Notify your own carrier as the policy requires. A check for the vehicle damage is separate from the injury claim, but read the paper before signing, because some releases cover both.
Taking an early offer is sensible only when the injury has genuinely ended, the bills are paid, nothing is owed to a health plan and the figure is close to what a lawyer would net for you after fees. That is rare in the first months.
See if you have a case
Three answers and a phone number. An attorney reviews your situation and calls you back, free.
Rear End Collision
$2,300,000
Insurer offered$85,000
Spinal cord injury after a rear end crash. The insurer offered $85,000.
T Bone Accident
$1,800,000
Insurer offered$120,000
Broken pelvis and internal bleeding at an intersection. The insurer offered $120,000.
Drunk Driver Victim
$1,500,000
Insurer offered$50,000
Traumatic brain injury caused by an impaired driver. The insurer offered $50,000.
Every case is different. Past results do not guarantee, warrant, or predict a similar outcome.
Send the offer letter, your declarations page and any records, and we tell you what the offer covers and what it leaves out. If it is fair we say so. If not, we take over the adjuster calls and build the demand. Top USA Law has no office in New Mexico; our team works with clients by phone and video anywhere in the state, and Andranik "Andy" Boyadzhyan, licensed in New Mexico, carries the file. Consultations are free and there is no fee unless we win. Read the New Mexico car accident lawyer page or call (877) 411-5291.
We serve New Mexico clients by phone, video and in person appointments arranged case by case.
Hurt in a crash? Talk it through for free.
New Mexico filing deadlines and insurance notice rules can be short. A free call tells you where your clock stands.
Last reviewed by Andranik "Andy" Boyadzhyan, Esq., September 2026.
Three fields. We respond fast, day or night.
Top USA Law took over everything after my car accident. They got me $450,000 when insurance only offered $15,000. I recommend them to everyone.
Client testimonials. Testimonials are not a guarantee, warranty, or prediction of the outcome of your case.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.