


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Missouri
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
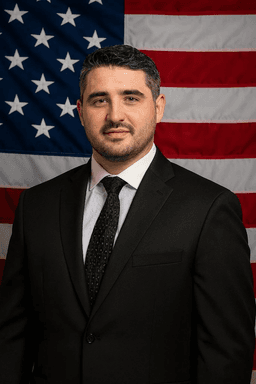 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Missouri.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Missouri, the first offer from the other driver's insurer is almost never the fair value of your claim. It arrives before your diagnosis is complete, it is priced on the assumption you will take it, and signing the release ends the claim for good. Top USA Law reviews any Missouri offer for free before you decide. Call (877) 411-5291.
Insurers offer early because an unknown injury is cheapest to buy before it is diagnosed, and a signed release closes the file forever.
The insurer offers early because an unknown injury is cheapest to buy before it is diagnosed, and a signed release closes the file forever. In the days after a rear end crash on Interstate 70 or a T bone at a Springfield intersection, you know your neck hurts and little else. The adjuster does not know either, and that uncertainty is priced in the insurer's favor. A small check, delivered with a sympathetic phone call and a one page release, ends the claim before an MRI can show a herniated disc.
Missouri gives the early offer a particular sting. There is no no fault coverage paying your bills in the background, so the first check can feel like the only money coming while the hospital sends statements. It is not. The at fault driver's liability policy, required under RSMo 303.025, owes the full value of the injury, and your own uninsured or underinsured motorist coverage may sit behind it. An early release gives all of that up.
Before answering, you need your diagnosis, your total losses, the policy limits on both sides and the liens waiting on the money.
A release ends the claim against the driver and the insurer for known and unknown injuries. If the neck strain turns out to be a disc injury that needs surgery a year later, the release still stands. Nothing in Missouri law requires you to answer an offer by the adjuster's date. The only hard deadline is the five year period to file suit under RSMo 516.120, plus the shorter notice terms in your own policy.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Thank the adjuster, decline the recorded statement and the blanket medical authorization, keep treating, and let a lawyer answer the offer in writing.
Thank the adjuster, decline the recorded statement and the blanket medical authorization, keep treating, and let a lawyer answer the offer in writing. You owe the other driver's insurer nothing beyond basic identification. Give them the crash report number if asked. Do not describe your injuries, do not estimate your own fault, and do not sign a medical release that reaches back ten years, because that history becomes the argument that your pain is old. Report the crash to your own carrier as your policy requires. Accepting a check for the car repair is different from releasing the injury claim, but read what you sign, because some releases cover both.
Accepting an early offer can be reasonable when the injury is truly over, every bill is paid, no lien exists and the number is close to what a lawyer would obtain after fees. That is uncommon in the first months. A free review costs an hour; a bad release costs whatever the claim was worth.
Send the offer letter, your declarations page and your records for a free review that shows plainly what the offer leaves out.
Send the offer letter, your declarations page and your records for a free review that shows plainly what the offer leaves out. The review can also show when an offer is fair. If it is not, a lawyer can take over communication with the adjuster and build the demand. Top USA Law does not keep an office in Missouri; our team works with clients across the state by phone and video, and Andranik "Andy" Boyadzhyan, licensed in Missouri, is the attorney on the file. The consultation is free and there is no fee unless we win, costs may apply. Read the Missouri car accident lawyer page or call (877) 411-5291.
Before you answer an adjuster, read the page for where you were hurt: the Kansas City car accident lawyer page, the St. Louis car wreck attorney page, or the Kansas City truck accident lawyer page if a semi hit you on I-70 or I-435.
We serve Missouri clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
You have five years to sue for an injury and three years after a death. A claim over a broken city street or sidewalk may need written notice to the mayor within 90 days.
A licensed Missouri attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Missouri claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.