


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Missouri
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
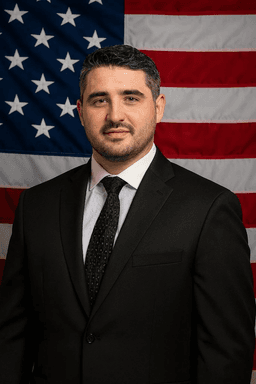 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Missouri.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Missouri, if the driver who hit you had no insurance, your own uninsured motorist coverage pays the claim, and every auto policy sold in the state must include it. The same coverage responds to a hit and run driver who is never found. Read every household policy to find what is available.
Your own insurer pays through the uninsured motorist part of your policy when the other driver has no policy or a lapsed one.
Your own insurer does, through the uninsured motorist portion of your policy. Missouri requires every driver to carry liability insurance, but a requirement is not compliance, and a driver with no policy, a lapsed policy or one cancelled for nonpayment can turn up after a crash. When that happens, the claim you would have made against the other driver's insurer is made against your own, for the same losses.
This is not a favor from your insurer. Uninsured motorist coverage is a contract you paid for, and Missouri law requires it in every auto liability policy issued in the state. The mandatory liability requirement sits in RSMo 303.025; the uninsured motorist requirement rides with it, so if you hold a Missouri policy at all, you hold this coverage. A relative's policy may cover you as well if you share a household.
Underinsured motorist coverage is different. It responds when the other driver has insurance but too little for your injuries, and it is optional in Missouri, so it exists only if someone in your household chose it. There is no state fund when neither exists. Then the claim rests on the driver personally, so identifying the driver comes first.
The claim is made against your own insurer, which can raise every defense the other driver could have raised, including partial fault.
The claim is made against your own insurer, but it is not a friendly conversation. Your insurer stands in the shoes of the driver who hit you and can raise every defense that driver could have raised: that you were partly at fault, that your injuries came from something else, that treatment ran too long. You must prove the uninsured driver was negligent and prove your damages. Policies can also require prompt notice, cooperation, and proof that the other driver was actually uninsured, such as a letter from that driver's former carrier or a police report noting no insurance.
Consider a driver rear ended on the interstate through St. Louis by someone whose insurance card is for a policy that lapsed the month before. The injured driver's own policy carries uninsured motorist limits, so the claim proceeds against that policy for the full value of the injury up to those limits. If a second policy exists in the household, both are examined for coverage that may add together.
A driver who leaves the scene and is never identified is treated as uninsured for purposes of the coverage. Leaving the scene is a crime under RSMo 577.060, and a later conviction is evidence in the civil case. A policy can require that a hit and run be reported to police within a set time and that there be physical contact or corroborating evidence, so the report and scene photographs matter. If the driver was also intoxicated, a conviction under RSMo 577.010 is evidence against the driver personally.
Start with the declarations page for every policy in your household and read the coverage, notice and consent terms. Written notice should go to your carrier immediately, and no settlement with another party should happen without the carrier's consent when the policy requires it, because doing so can forfeit the coverage. The deadline to sue the uninsured driver remains five years under RSMo 516.120; the contract deadline under your policy can be shorter, so both deadlines belong on the calendar.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
An uninsured motorist claim that cannot be settled is filed in the circuit court for the county where you were hurt.
An uninsured motorist claim that cannot be settled is filed in the circuit court for the county where you were hurt, such as the Circuit Court of Jackson County or the Circuit Court of the City of St. Louis. Records from the Level I trauma centers, including Research Medical Center in Kansas City, SSM Health Saint Louis University Hospital and University of Missouri Health Care in Columbia, are requested in the first weeks. Andranik "Andy" Boyadzhyan is the firm's Missouri licensed attorney. Start with the Missouri car accident lawyer page or call (877) 411-5291 to have your policies reviewed.
Uninsured drivers cause crashes in every part of Missouri. Our St. Louis car accident lawyer page covers I-64 and I-44, the Independence car crash attorney page covers Noland Road and I-470, and the Springfield car accident attorney page covers Glenstone Avenue.
We serve Missouri clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
You have five years to sue for an injury and three years after a death. A claim over a broken city street or sidewalk may need written notice to the mayor within 90 days.
A licensed Missouri attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Missouri claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.