


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Alabama
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
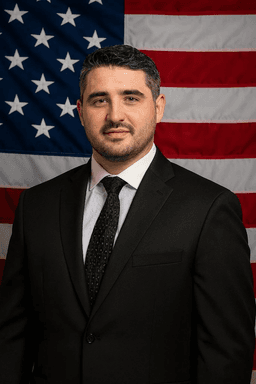 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Alabama.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Alabama, the other driver's insurer can make its first offer before your injury has declared itself, and prices it on the state's contributory negligence rule, which the adjuster may mention in the same breath. Sign the release and the claim is over for good. Top USA Law will look at any offer at no charge. Call (877) 411-5291.
Insurers offer early because a small payment before the injury is understood closes the file cheaply, and Alabama's fault rule adds pressure.
Because paying a small sum before the injury is understood, and before you know how fault works here, closes the file cheaply. In the first weeks after a crash on US 280 or I-20/59 you do not know whether your back pain is a strain that will ease or a herniated disc that will need injections. Neither does the adjuster, and the number on the table is built on that uncertainty while it lasts.
Alabama gives the early offer a particular edge. Under contributory negligence, a jury finding that you were even slightly at fault can bar the entire claim. Adjusters raise that risk early, so that a few thousand dollars looks like the safe choice. Whether any evidence supports the fault argument is something they would rather you never ask.
The money is paid for a signature on a release, and the release gives up every claim you have from the crash: pain and suffering, wages after the first weeks, future medical care. Alabama has no cooling off period for it. A later MRI that shows what the offer assumed was not there changes nothing.
Know where your treatment stands, what the fault evidence shows, how much coverage exists, what you have lost, and who holds a lien.
Decline the recorded statement, do not sign a medical release that reaches your whole history, and let the adjuster know a lawyer will call. Keep every appointment. Say nothing online about the crash or your activities. No Alabama rule obliges you to accept or reject by the insurer's date; the deadline that matters is the two years to file suit under Ala. Code 6-2-38, and, for a crash involving a city or county vehicle, the sworn claim due within months.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Accepting early makes sense only when the injury has run its course, every loss is counted, fault is undisputed and the offer nears full value.
Only when the injury has run its course, every bill, wage and lien is accounted for, fault is undisputed, and the figure nears full value. All four may not line up in the first months, and in Alabama the fault question alone deserves a look from someone who has seen how contributory negligence plays in front of a Jefferson County or Madison County jury. An hour with the file is free. The release is forever.
Some early offers come from your own insurer, not the other driver's. If the driver who hit you had no coverage, who pays after a crash with an uninsured Alabama driver explains that claim.
Send the offer letter and your records for a free review of what the offer leaves out. A fair offer gets a straight answer.
Send the offer letter, your declarations page and whatever records you have for a free review, in plain words, of what the offer leaves out. A fair offer gets a straight answer: take it. A poor one goes to Andranik "Andy" Boyadzhyan, who is licensed in Alabama, to build the fault evidence and, if the insurer will not move, to file in the Circuit Court of the county where the crash happened. Top USA Law has no Alabama office; consultations are by phone or video. The review is free and there is no fee unless we win, costs may apply. Read the Alabama car accident lawyer page, or call (877) 411-5291 first and sign nothing until we have talked.
Before you accept, read the page for where the wreck happened: the Birmingham car accident attorney page, the Mobile car wreck lawyer page for I-10 and Airport Boulevard, or the Huntsville car crash attorney page for I-565.
We serve Alabama clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
Sue a driver within two years. File a city claim in six months or a county claim in 12 months, then wait before suing a county.
A licensed Alabama attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Alabama claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.