

Rear End Collision
$2,300,000
Insurer offered$85,000
Spinal cord injury after a rear end crash. The insurer offered $85,000.
Serving Washington, D.C.
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
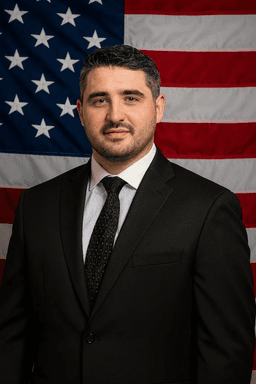 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Washington, D.C.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Washington, D.C., when the driver who hit you carried no insurance, the uninsured motorist coverage on your own policy steps in and pays what that driver's insurer should have paid, pain and suffering included. The District requires that coverage on every registered vehicle, and a household relative's policy may respond too. There is no public fund. Top USA Law tracks down every policy that can pay. Call (877) 411-5291.
Your own auto insurer pays, through the uninsured motorist coverage the District requires on every policy, standing in for the driver who had none. You prove the other driver was at fault and what the crash did to you, and your insurer pays the medical costs, wages and pain and suffering that driver owed, up to your uninsured motorist limit.
District law requires liability coverage and uninsured motorist coverage on every registered vehicle, and underinsured motorist coverage, which fills the gap when the other driver's policy is too small, is available and worth carrying. Even so, drivers on I-395 and Benning Road NE are hit every week by people with lapsed policies or borrowed cars, and the mandatory coverage exists because of them.
Two things are missing in the District. There is no public fund for victims of uninsured drivers, so a policy has to be found, whether yours, a relative's or the one on the car you were riding in. And unless you elected no fault benefits under D.C. Code section 31-2404, nothing pays automatically. Every dollar comes from a claim that has to be proved.
You notify your insurer promptly, prove the other driver's fault and your losses, and negotiate or arbitrate the value under your policy's terms. Uninsured motorist coverage follows people as well as cars, so a passenger may claim under the policy on the car and under a policy held at home, and a relative who lives with you may have coverage that responds to your crash. Each policy has its own limit, and the total available is often more than any one page shows.
In an uninsured motorist claim your own company stands in the shoes of the driver who hit you. It can raise every defense that driver could have raised, and in the District the biggest one is contributory negligence: if it can show that you, as a driver or passenger, were even slightly at fault, it can deny the whole claim. A pedestrian or cyclist gets the gentler rule in D.C. Code section 50-2204.52 and recovers unless more than 50 percent at fault.
When the driver leaves and is never identified, the policy treats the unknown driver as uninsured. Leaving after a collision is a crime under D.C. Code section 50-2201.05c, and the Metropolitan Police Department report you file starts both the search for the driver and the insurance claim. Report it the same day if you can; most policies require a prompt police report for an unidentified driver.
Then the claim runs against the driver personally, which is worth pursuing only when that driver has wages or property to collect against. Before reaching that point we check the vehicle's owner, who may be insured even when the driver was not, any employer if the driver was working, and whether a District vehicle or a dangerous District maintained road contributed. A claim against the District government requires written notice to the Mayor within six months under D.C. Code section 12-309, so we ask at the first meeting.
See if you have a case
Three answers and a phone number. An attorney reviews your situation and calls you back, free.
Rear End Collision
$2,300,000
Insurer offered$85,000
Spinal cord injury after a rear end crash. The insurer offered $85,000.
T Bone Accident
$1,800,000
Insurer offered$120,000
Broken pelvis and internal bleeding at an intersection. The insurer offered $120,000.
Drunk Driver Victim
$1,500,000
Insurer offered$50,000
Traumatic brain injury caused by an impaired driver. The insurer offered $50,000.
Every case is different. Past results do not guarantee, warrant, or predict a similar outcome.
We identify every household policy in the first conversation, send the notices each policy requires, and protect the fault evidence that decides the claim. A licensed attorney runs the claim against your insurer the way it would run against a stranger, and when the driver is later found, pursues the driver and the coverage together. Cases that do not settle are filed in the Superior Court's Civil Division. Our District listing is at 700 12th Street NW. There is no charge for the consultation and no fee unless we win. Read the Washington, D.C. car accident lawyer page or call (877) 411-5291 with your policy's declarations page nearby.
We serve Washington, D.C. clients by phone, video and in person appointments arranged case by case.
Hurt in a crash? Talk it through for free.
Washington, D.C. filing deadlines and insurance notice rules can be short. A free call tells you where your clock stands.
Last reviewed by Andranik "Andy" Boyadzhyan, Esq., September 2026.
Three fields. We respond fast, day or night.
I was in an Uber that got T boned. Both insurance companies were pointing fingers. Top USA Law cut through the mess and got me $875,000.
Client testimonials. Testimonials are not a guarantee, warranty, or prediction of the outcome of your case.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.