


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Missouri
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
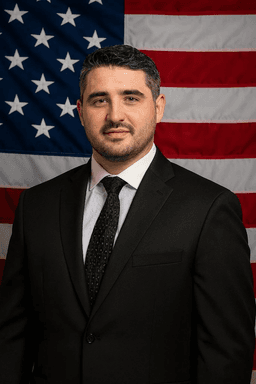 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Missouri.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Missouri, when the driver who hurt you is uninsured or leaves before being identified, your own uninsured motorist coverage pays your injury claim, subject to its terms. Auto liability policies must include it, though commercial vehicles and employer fleets of five or more passenger vehicles need only be offered it. Call Top USA Law, (877) 411-5291.
Missouri auto liability policies must include uninsured motorist coverage; commercial vehicles and employer fleets of five or more passenger vehicles need only be offered it.
RSMo section 379.203 starts with a ban. No auto liability policy may be "delivered or issued for delivery in this state" for a vehicle "registered or principally garaged in this state" unless uninsured motorist coverage "is provided therein or supplemental thereto". The coverage protects people insured under the policy who are "legally entitled to recover damages" from an uninsured owner or driver. It reaches bodily injury, sickness and disease, "including death".
In plain words: if you buy auto liability insurance on a Missouri car, uninsured motorist coverage comes with it. When a driver with no insurance hurts you, you claim against your own insurer for what that driver would have owed you. The Missouri Department of Commerce and Insurance puts it the same way on its auto insurance FAQ page: an insurer "cannot issue a contract of automobile liability coverage in Missouri without including uninsured motorist coverage on the policy."
There is one carve-out. For a commercial motor vehicle, and for an employer with a fleet of five or more passenger vehicles, the coverage need only be "offered", so a business policy may not include it. Andranik "Andy" Boyadzhyan, Attorney at Law, licensed in Missouri, wrote this guide for Top USA Law.
It pays for bodily injury, sickness, disease and death caused by an uninsured driver, up to the policy limit; it does not repair your car.
The statute ties the coverage to bodily injury "including death". Missouri's insurance regulator agrees. Its FAQ says the coverage "applies to bodily injury only" and "does not cover damage to your vehicle." It also says the coverage guards against hit and run drivers and follows you on foot. A dented car is a matter for collision coverage, if you carry it, or for a claim against the driver once found.
The floor is "not less than the limits for bodily injury or death set forth in section 303.030." Under RSMo section 303.030, that means 25,000 dollars per injured person and 50,000 dollars for all the people hurt in one crash. Past results do not guarantee a similar outcome. You can buy more. Your declarations page lists the amount. Underinsured coverage is different: it is optional in Missouri, and it helps when the other driver had some insurance but not enough. If you buy it, RSMo section 379.204 treats limits below twice the state minimum as sitting "in excess of the liability coverage" of the other driver.
Yes. The statute says the right to recover exists even when the driver "departed the scene" before anyone could identify them. It "also exists whether or not physical contact was made" with you or your car. So a driver who ran you off Interstate 70 and kept going can support a claim. The policy terms and your proof still matter.
Under 379.203, an insured vehicle counts as uninsured, "subject to the terms and conditions of such coverage", when its liability insurer cannot pay "because of insolvency". The protection applies only if that insurer becomes insolvent within two years after the accident and your own uninsured motorist coverage was in effect when the accident happened.
Yes. After paying you, your insurer is "entitled to the proceeds of any settlement or judgment" you later recover from the person legally responsible, to the extent of what it paid. If the driver is found and has assets or insurance, expect your insurer to claim a share of that recovery.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Notify police and your insurer, file Missouri's uninsured accident report if required, follow your policy's notice rules, and sue the driver within five years.
Missouri has its own report for these crashes. Under RSMo section 303.040, when an accident with an uninsured motorist kills or injures someone, or causes more than five hundred dollars of damage to one person's property, the owner or driver must "report the matter in writing to the director" of revenue "within thirty days after such accident." The Department of Revenue calls it Form 1140, and its FAQ says the form may be filed for an accident under a year old. The report also helps the claim: when the other driver never files one, 379.203 makes that "prima facie evidence of uninsured status", meaning it proves the point unless the insurer shows otherwise. The insurance regulator lists the Drivers License Bureau at 573-751-7195 for uninsured crashes.
An uninsured motorist claim is still a fault claim. Your company steps into the shoes of the driver who hurt you and asks what that driver would owe. If you were partly to blame, Missouri's pure comparative fault rule, adopted in Gustafson v. Benda (661 S.W.2d 11, Mo. banc 1983), trims the amount by your percentage. It does not automatically bar the claim, though someone found entirely at fault recovers nothing. Save the police report, photos, witness names and medical records.
Suing the uninsured driver for an injury must happen within five years (RSMo section 516.120); a family suing over a death has three years from the date of death (RSMo section 537.100). Do not wait on either. Your policy can set separate notice and cooperation duties, so read it promptly. A claim against a city over a street, sidewalk or bridge defect can need written notice to the mayor within 90 days (RSMo section 82.210).
Top USA Law's main office is in Hackensack, New Jersey, and we handle Missouri claims by phone, video and in-person meetings we arrange. Read uninsured driver claims in Missouri, St. Louis hit and run claims and Missouri insurance minimums, or call (877) 411-5291. No Fee Unless We Win (Costs May Apply).
We serve Missouri clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
You have five years to sue for an injury and three years after a death. A claim over a broken city street or sidewalk may need written notice to the mayor within 90 days.
A licensed Missouri attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Missouri claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.