


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Alabama
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
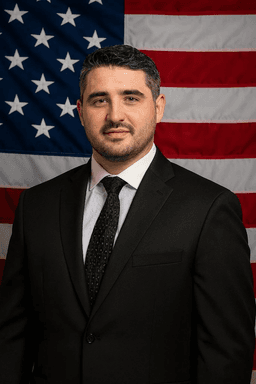 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Alabama.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Alabama, when your insurer totals your car, state rules let it offer a comparable replacement or pay what a comparable car would cost, taxes and fees included, less your deductible. Any other basis must be documented and itemized. Call Top USA Law, (877) 411-5291.
Under Alabama's claims rule, the insurer may offer a comparable replacement or pay the cost of a comparable car, including taxes and fees.
The Alabama Department of Insurance's Regulation 125 sets the standard for prompt, fair and equitable settlement of automobile claims. Rule 482-1-125-.08 says that when a policy settles a first-party total loss on actual cash value or replacement with a car of like kind and quality, one of three paths applies. The insurer may offer a replacement car from the same manufacturer, of the same or a newer year, with a similar body style, options and mileage, in as good or better overall condition, available for inspection within a reasonable distance of your home, with all taxes and fees paid and nothing owed beyond your deductible. Or it may pay cash based on the actual cost, less the deductible, of buying such a car, "including all applicable taxes, license fees and other fees incident to the transfer of ownership." The tax and fee part is limited to what would have been paid on the totaled car at the time of settlement. The third path is any other basis, which "must be supported by documentation giving particulars of the automobile condition."
The Department's auto FAQ says a car can be considered a total loss when the damage is 75 percent or more of its value, and the Department of Revenue's salvage FAQ describes the same threshold against fair retail value taken from a nationally recognized compilation. The Department's FAQ also says it has no regulatory authority over the monetary evaluation of your vehicle, so the number itself is a negotiation backed by the rule's documentation duties.
Top USA Law's main office is in Hackensack, New Jersey, and we meet Alabama clients by phone, by video and in arranged meetings. This page was written by Andranik "Andy" Boyadzhyan, Attorney at Law. Our work is injury claims; if you were hurt in the crash that totaled your car, the car claim and the injury claim are two different things.
Ask for the valuation in writing; Alabama's rule says betterment deductions must be measurable, itemized, specified in dollars and documented in the claim file.
Paragraph (8)(a) of the rule allows betterment deductions only if they reflect a measurable decrease in market value caused by the car's poorer condition or prior damage, and reflect its overall condition, considering age, for wear and tear or rust and for missing parts. A deduction for a missing part cannot exceed the replacement cost of that part. Under (8)(b) each one must be measurable, itemized, specified as to dollar amount and documented in the claim file, and paragraph (5) says the same of any reduction for betterment or depreciation. Paragraph (1)(c) adds that deductions from a total loss cost, including a deduction for salvage, must be measurable, discernible, itemized and specified as to dollar amount, and that the basis must be fully explained to you. Ask the insurer to send each item.
Send comparable cars in your area with the same year, options and mileage, plus maintenance records, new tires and photos of the car before the crash. A comparable car in the rule is measured by manufacturer, year, body style, options, mileage and condition, so a comparison that misses one of those is the place to push. If the insurer will not move, the Department of Insurance takes complaints online, by mail and by phone at 334-241-4141. Its page says it can require corrective action when an insurer fails the policy's legal obligations, but it cannot determine the value of a claim or fault, and it cannot assist with a complaint if you have an attorney.
Paragraph (7) says that before it stops paying storage charges, the insurer must give you reasonable notice and a reasonable time to remove the car from storage.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
On your policy, an insurer has 30 days after proofs of loss, or the days the policy sets, to accept, deny or explain a delay.
Rule 482-1-125-.07 says that within thirty days, or the number of days the policy specifies, after receiving properly executed proofs of loss, the first-party claimant must be advised of acceptance or denial. A denial must cite the policy provision relied on. If the insurer needs more time, it must say so within that period with its reasons, and then update you 45 days after the first notice and every 45 days after that. Once liability is accepted and the amount and documents are settled, the insurer must tender payment within thirty days, or the time the policy specifies. For an unresolved claim near a statute of limitations, an insurer must send a claimant without a lawyer written notice of the expiration date approximately 45 calendar days before it.
Under Alabama's contributory negligence rule, your own negligence that helped cause the crash may bar a negligence claim; collision coverage is another route.
The Department's FAQ lists two options: claim against the at-fault driver's insurer, or, if you have collision coverage, have your own insurer pay. Under Alabama's common law, contributory negligence bars an ordinary negligence claim when your own negligence proximately helped cause the crash; it is no defense to a wantonness claim. Your own collision coverage is a contract claim and does not depend on that rule. The minimum property damage limit in Ala. Code section 32-7-6 is 25,000 dollars, and a car worth more than the other driver's limit can leave a gap. Past results do not guarantee a similar outcome. Ask whether your insurer will seek your deductible back from the other side.
The car claim and the injury claim are separate, so sign only a release that is limited to the vehicle.
Alabama has no no-fault coverage, so medical bills do not come from the total loss payment. Uninsured motorist coverage is part of an Alabama auto policy unless the named insured rejects it, under Ala. Code section 32-7-23, and you can check your declarations page. A car check can arrive with paperwork, so read what it releases before you cash it.
An injury suit is due within two years under Ala. Code section 6-2-38(l). An ordinary negligence claim for damage to a car also falls under the two years of section 6-2-38(l), which covers injury to the rights of another not specifically listed; do not assume the six years that Ala. Code section 6-2-34 gives for trespass to or conversion of personal property. Plan on two years. If a city vehicle was involved, Ala. Code section 11-47-23 says tort claims against a city "shall be presented within six months from the accrual thereof or shall be barred." For a personal injury claim, section 11-47-192 also requires a sworn statement filed with the city clerk by the injured person, or the personal representative after a death, stating substantially how the injury happened, the day, time and place, and the damages claimed. A claim against a county must be presented to the county commission within 12 months under section 11-12-8, with a minor's or incapacitated person's 12 months running from removal of the disability, and under section 6-5-20 suit waits until the commission disallows or reduces the claim, or fails to act for 90 days.
See the Alabama car accident lawyer page and the Alabama herniated disc guide, or call (877) 411-5291. No Fee Unless We Win (Costs May Apply).
We serve Alabama clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
Sue a driver within two years. File a city claim in six months or a county claim in 12 months, then wait before suing a county.
A licensed Alabama attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Alabama claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.