


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Missouri
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
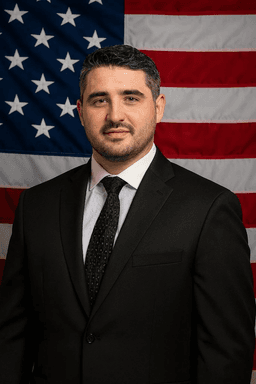 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Missouri.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Missouri, if an uninsured driver hurt you, your own uninsured motorist coverage pays the injury claim up to its limits; most Missouri auto policies must include it. Car damage goes to your collision coverage, if you bought it. If you had no insurance yourself, read on. Call Top USA Law, (877) 411-5291.
Your own uninsured motorist coverage stands in for the missing policy on injuries; your collision coverage, if you bought it, handles the car.
Missouri is a fault state with no personal injury protection, the no-fault medical coverage some states require. So when the driver who caused the crash carried nothing, there is no policy on that side to send your bills to. Missouri fills that gap from your side of the claim. RSMo section 379.203 bars an auto liability policy for a car registered or principally garaged in Missouri unless uninsured motorist coverage is provided in it, at no less than the limits in section 303.030. For a commercial motor vehicle or an employer with a fleet of five or more passenger vehicles, the coverage need only be offered. The Department of Commerce and Insurance says the same in its consumer FAQ: a company cannot issue auto liability coverage in Missouri without including uninsured motorist coverage.
The department adds two limits worth knowing on day one. Uninsured motorist coverage "applies to bodily injury only," and it "does not cover damage to your vehicle." It does reach a hit and run: under 379.203, the coverage applies even though the other driver left before being identified, and whether or not the two vehicles touched. The department also says the coverage protects you as a pedestrian struck by an uninsured driver.
Top USA Law's main office is in Hackensack, New Jersey, and we meet Missouri clients by phone, by video and in meetings we arrange. Andranik "Andy" Boyadzhyan, Attorney at Law, licensed in Missouri, wrote this page. You pay no fee unless we win, and costs may apply.
It pays what the uninsured driver would owe for your injuries, up to your policy limit, minus any share of fault that is yours.
The floor comes from section 303.030: not less than 25,000 dollars for one person's bodily injury or death in one accident and 50,000 dollars for two or more people. Your policy may carry higher limits; the declarations page sets your number. Past results do not guarantee a similar outcome. The claim is valued like any injury claim against a driver: medical bills, lost pay, pain and suffering, and what treatment still lies ahead.
Your own fault matters. Missouri follows pure comparative fault, adopted by the Missouri Supreme Court in Gustafson v. Benda (1983), and the department's FAQ describes it the same way: your damages are reduced by the percentage you are at fault. A driver found 20 percent responsible recovers 80 percent of the damages.
That is an underinsured driver, not an uninsured one. Missouri does not require underinsured motorist coverage, but if you bought it, RSMo section 379.204 says coverage with limits below twice the 303.020 bodily injury limits "shall be construed to provide coverage in excess of the liability coverage of any underinsured motor vehicle involved in the accident." Check every policy in your household for both coverages before you speak with an adjuster.
After it pays, your insurer is entitled under 379.203.4 to the proceeds of any settlement or judgment against the person legally responsible, up to what it paid. That is one reason to tell your insurer before settling anything with the uninsured driver directly.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Call police, tell your insurer promptly, and if you drove or owned a car in a qualifying crash, report it to the Department of Revenue.
Get the other driver's name, plate and license, photographs of both vehicles and the scene, and the police report number. Then give your own insurer prompt notice under the policy's terms, which can set their own deadlines.
The state report is separate. Under RSMo section 303.040, the operator or owner of a vehicle involved in a Missouri accident with an uninsured motorist, where someone was killed or injured or one person's property damage was over five hundred dollars, "shall, within thirty days after such accident, report the matter in writing to the director" of revenue. The Department of Revenue's mandatory insurance FAQ says you may file its Motor Vehicle Accident Report, Form 1140, if the accident happened less than one year ago, and gives its mailing address: Missouri Department of Revenue, 301 West High Street, Room 470, PO Box 200, Jefferson City, MO 65105-0200. File within the statute's 30 days rather than relying on the longer window in the FAQ. The Department of Commerce and Insurance points people to the Driver License Bureau at 573-751-7195. Section 379.203.5 adds a practical reason: an owner's or operator's failure to file that report is prima facie evidence, meaning evidence that stands unless rebutted, that the vehicle was uninsured.
You can face a misdemeanor and license penalties, and Missouri law can cut your pain and suffering claim against a properly insured driver.
RSMo section 303.025 bars an owner from operating, registering or keeping a vehicle registered without the financial responsibility Missouri law requires. A first violation is a class D misdemeanor, and the court also suspends the license, assesses four points or orders supervision. The department's FAQ adds that a driver at fault who fails to pay for the damage can face a one-year license suspension unless the claim is paid, settled or secured.
Under RSMo section 303.390, an uninsured driver waives the ability to collect noneconomic loss, meaning pain and suffering, from a driver alleged to be at fault who is "in compliance with the financial responsibility laws", meaning that driver carried the required insurance or other proof, and any award is reduced by that part. The rule reaches an uninsured owner who was driving, an uninsured driver using the car with permission, and one using it without permission. Exceptions apply: the waiver does not apply if the crash was caused in whole or in part by a driver under the influence of drugs or alcohol, or by one convicted of a listed involuntary manslaughter offense (the statute also names an assault offense, but the revisor notes that the section it points to was transferred and the new section does not contain that language); it does not apply to someone whose previous policy ended for nonpayment without at least six months' notice before the crash; and passengers in the uninsured car are not subject to it. Economic loss, such as medical bills and lost wages, can still be claimed, and your own share of fault still reduces it. The rule is also under challenge: in Jiles v. Schuster Co. (2018), a federal court in Missouri held that it violates the right to a jury trial under the Missouri Constitution. That ruling does not bind Missouri's state courts, so an insured driver can still raise the waiver.
A passenger keeps the full claim against whichever driver caused the crash. If the driver of the car you rode in caused it and had no coverage, your own household policy's uninsured motorist coverage may respond, by its terms.
An injury suit against a driver must be filed within five years under RSMo section 516.120. A wrongful death action must be brought within three years of the death under RSMo section 537.100. A claim under your own policy can carry its own notice and suit terms, so read them. If a city or county employee's negligent driving in the course of employment caused the crash, RSMo section 537.600 waives sovereign immunity, meaning the government's usual protection from being sued, and RSMo section 537.610 caps the recovery. Under RSMo section 508.010, a suit by someone first injured in Missouri is filed in the county where the plaintiff was first injured.
See being hit by an uninsured driver in Missouri, the RSMo 379.203 guide, Missouri total loss claims and the Missouri car accident lawyer page, or call (877) 411-5291. No Fee Unless We Win (Costs May Apply).
We serve Missouri clients by phone, video and in person appointments arranged case by case, and calls are answered 24 hours a day.
You have five years to sue for an injury and three years after a death. A claim over a broken city street or sidewalk may need written notice to the mayor within 90 days.
A licensed Missouri attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Missouri claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.