


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Washington, D.C.
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
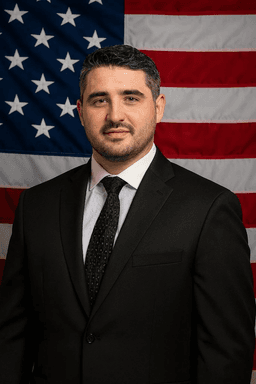 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Washington, D.C.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Washington, D.C., having no insurance of your own does not by itself end your injury claim against the driver who caused the crash, but District fault rules still apply. Driving uninsured is a separate violation with fines and a possible suspension. Top USA Law can review your options. Call (877) 411-5291.
Yes. Driving uninsured brings its own fines, but your claim against the driver who caused the crash still turns on fault and proof.
This page is for the person who had no policy at the time of the crash. Maybe the policy lapsed. Maybe you drove a car with no coverage, or you never owned a car at all. If the other driver was the one without insurance, read our page on being hit by an uninsured driver in Washington, D.C. instead. The question here is different: what you can still recover, and what being uninsured costs you.
The District sets the rules in two places. D.C. Code 31-2403 requires every owner of a car registered in the District to keep insurance in effect for the whole registration period. The amounts come from D.C. Code 31-2406. A nonresident may not drive here without it either. D.C. Code 31-2413 makes it an offense to own, drive or let someone drive a vehicle without that insurance. Neither section takes away an injured person's claim against someone else who caused the crash. Andranik "Andy" Boyadzhyan, licensed in the District, wrote this guide; Top USA Law's main office is at 411 Hackensack Ave in Hackensack, New Jersey, and the firm's Washington, D.C. office listing is 700 12th St NW, Suite 700.
Driving without required insurance can bring a civil fine and a license suspension, and the registration can be suspended until coverage is shown.
D.C. Code 31-2413(b)(1)(A) sets the penalty for operating, or letting someone operate, a vehicle in the District without required insurance: a civil fine of $500, a license suspension for up to 30 days, or both, for a first offense, with a 50 percent higher fine or a suspension of up to 60 days for later offenses. An owner whose registered car simply had no coverage faces a separate fine under 31-2413(b)(2)(A): $150 for the first 1 to 30 days, then $7 a day, up to $2,500 for each violation, which the Director can waive on proof the car was not driven. Past results do not guarantee a similar outcome.
Under D.C. Code 31-2403(d)(2), the Director suspends the registration 30 days after mailing a notice unless the owner proves the car is insured and pays the fines, and a suspended car can be immobilized until insurance is in effect. These are penalties for the lapse. They do not decide who caused the crash.
You can claim against the at-fault driver's insurer, though slight fault can bar a car's driver or passenger under District common law.
The main claim is against the driver who caused the crash, paid by that driver's liability insurer. District minimums under D.C. Code 31-2406 are 25,000 dollars per person and 50,000 dollars per accident for injury, and 10,000 dollars for property damage. The claim can cover medical bills, lost pay and pain and suffering. Under District of Columbia common law, a driver or passenger of a car who is found even slightly at fault may be barred from recovering. A pedestrian, cyclist, motorcyclist or other vulnerable user is barred only if their own negligence was a proximate cause and greater than the combined negligence of all the defendants, under D.C. Code 50-2204.52.
Other coverage depends on whose policy reaches you. Personal injury protection is optional in the District, and under D.C. Code 31-2404 it applies only to a victim who is an insured, or an occupant of the insured's vehicle or of a vehicle the insured is driving. So a passenger in a friend's insured car may claim that car's PIP if its owner bought it, even with no policy of their own. Uninsured motorist coverage under D.C. Code 31-2406(f) protects "persons insured thereunder", so a household relative's District policy covers you only if its terms make you an insured. Ask every relative you live with for their declarations page. Health insurance, if you have it, pays medical bills whatever the cause.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Then the claim runs against the at-fault driver personally, and any District policy that covers you, such as a relative's, may provide uninsured motorist coverage.
With no policy on either side, there are fewer places to look. A claim can still be brought against the at-fault driver, and the owner if someone else owned the car, but collecting depends on what that person has. If any District policy covers you as an insured, its uninsured motorist coverage can stand in for the driver who had none: D.C. Code 31-2406(f) defines an uninsured motor vehicle to include one "not insured by a motor vehicle liability policy applicable to the accident". The passenger in an insured car is the other common route, through that car's policy.
Health insurance and Medicaid, if you have them, pay treatment. Keep every bill, because a District hospital can hold a lien on any later recovery for its reasonable charges under D.C. Code 40-201 (not for an injury covered by workers' compensation), once the notice D.C. Code 40-202 requires is filed with the Recorder of Deeds and mailed before payment. If you were working when the crash happened, workers' compensation may cover you whatever your auto coverage was.
Get care, collect the other driver's insurance information and police report, and avoid recorded statements to the other insurer until you get advice.
Three years to sue a private driver; District claims need Mayor notice in six months; any PIP election is due within 60 days.
| Step | Deadline | Rule |
|---|---|---|
| Lawsuit against the at-fault driver | Three years from the crash | D.C. Code 12-301 |
| Claim against the District, such as a city vehicle or road defect | Written notice to the Mayor within six months of the injury | D.C. Code 12-309 |
| PIP election, if a policy you ride under carries PIP | Within 60 days of the crash | D.C. Code 31-2405 |
| Registration suspension notice | Suspension takes effect 30 days after the mailed notice unless proof is shown | D.C. Code 31-2403 |
A District lawsuit is filed in the Superior Court of the District of Columbia, Civil Division, at the Moultrie Courthouse, 500 Indiana Avenue NW. For crashes on the other side of the line, our New Jersey and New York guides explain those states' rules, which differ. Call (877) 411-5291 for a free review. No Fee Unless We Win (Costs May Apply).
Sue within three years, or two after a death. District claims need Mayor notice in six months; elect PIP in 60 days.
A licensed Washington, D.C. attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Washington, D.C. claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.