


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Washington, D.C.
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
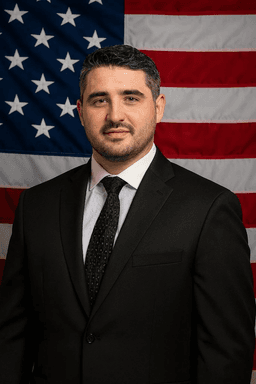 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Washington, D.C.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Washington, D.C., health insurance pays crash medical bills first if you have it, because PIP is optional and generally pays only after other coverage is used up, except for a deductible. Electing PIP within 60 days limits any suit against another person unless the District threshold is met or your costs exceed PIP. Call for a free case review.
Key takeaways
Yes. Health insurance you are eligible for pays first; optional PIP, if bought and elected within 60 days, pays your deductible and the rest.
New York and New Jersey make injury coverage part of every auto policy. The District does not. Under D.C. Code section 31-2404, insurers must offer personal injury protection, but you choose whether to buy it, and in what combination. So a person hurt at the 14th Street Bridge or on Benning Road NE may arrive at MedStar Washington Hospital Center with only a health insurance card. That card works for crash care, subject to the plan's rules. The table shows who pays in common situations.
| Your coverage | Who pays medical bills | What to watch |
|---|---|---|
| Health insurance, no PIP | Your health plan, under its deductibles and network rules | The claim against the at-fault driver for what the plan did not pay |
| PIP bought and elected within 60 days | Your health plan or other coverage first; PIP for your deductible and for what remains, up to the medical limit you bought (D.C. Code 31-2406(g)) | Electing PIP limits any suit against another person unless a threshold is met or your medical or work-loss costs exceed PIP (D.C. Code 31-2405) |
| PIP bought but not elected in 60 days | Health insurance; the liability coverage applies instead of PIP | Full claim against the at-fault driver, subject to fault rules |
| Hurt on the job while driving | Workers' compensation; PIP is reduced by those benefits | D.C. Code 31-2410(b) |
Elected within 60 days, PIP pays medical, work loss and funeral costs after health insurance is used up, for the insured and their car's occupants.
Under D.C. Code section 31-2404, PIP covers medical and rehabilitation expenses, meaning "all reasonable charges incurred for reasonably necessary products, services, and accommodations" for your care, recovery or rehabilitation. The medical coverage must be at least $50,000, with packages of $50,000 and $100,000. Past results do not guarantee a similar outcome. You may buy medical, work loss and funeral coverage in any combination. PIP applies only to a victim who is an insured, or an occupant of the insured's vehicle or a vehicle the insured is driving. A provider must be licensed or approved for PIP to pay it. Our guide to the D.C. PIP option covers the benefit details.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
Yes, within 60 days. Electing PIP limits any suit against another person unless the injury or costs pass a legal threshold.
Under D.C. Code section 31-2405, a victim must tell the PIP insurer within 60 days of the crash whether they elect PIP benefits. The insurer must notify you of the deadline in writing, and it can be extended only by written agreement. If you elect PIP, you may sue another driver only in two cases. The first is an injury that meets the statutory threshold: substantial permanent scarring or disfigurement, a substantial permanent impairment that significantly affected your work or daily life, or an impairment that kept you from all or substantially all usual activities for more than 180 continuous days. The second is cost: your medical and rehabilitation expenses or work loss exceed the PIP available. If you make no election, the liability coverage applies. Survivors may bring a death claim either way. Our D.C. pain and suffering page explains that tradeoff.
Health insurance or other coverage you qualify for pays first; PIP, elected within 60 days, pays after it is used up, plus the deductible.
D.C. Code section 31-2410(f), titled "Primacy of personal injury protection," now reads "Repealed." Subsection (b) says workers' compensation and government-required temporary disability benefits are subtracted when PIP is figured. The exception is when the law providing them makes them secondary. Nothing in that section tells a health plan to pay first or second, but D.C. Code section 31-2406(g) does: "A victim is prohibited from claiming personal injury protection benefits under this chapter, other than to compensate for any deductible, if the victim is eligible for compensation for the loss covered by personal injury protection from another insurer or another insurance coverage, unless the victim has exhausted benefits offered by the insurer or insurance coverage." So health insurance or other coverage you are eligible for pays first, and PIP pays your deductible and what remains after that coverage is used up. The coordination of benefits terms in your health plan and your auto policy apply within that rule, and PIP is still reduced by workers' compensation. Ask each insurer, in writing, how it coordinates with the other. Subsection (a) also bars a PIP deductible from applying to emergency medical, ambulance or hospital services in the first 72 hours after the crash.
Yes. The at-fault driver's liability coverage pays proven medical costs, but under District common law, any fault can bar a car driver's claim.
Every District policy must carry liability coverage of at least $25,000 per person and $50,000 per accident under D.C. Code section 31-2406. Past results do not guarantee a similar outcome. Medical bills your health plan paid, and those it did not, are part of the damages you can claim. Under District of Columbia common law, a driver or passenger found even slightly at fault can lose the claim. Pedestrians, cyclists and motorcyclists have more protection under D.C. Code section 50-2204.52: their negligence bars recovery only if it was a proximate cause and greater than the defendants' combined negligence. If the at-fault driver is uninsured, your mandatory uninsured motorist coverage can pay. The deadline to sue is three years under D.C. Code section 12-301. See partial fault in D.C..
It depends on your plan's terms and the law that governs it. Your lawyer must keep any disputed amount separate until it is resolved.
We did not find a District statute in our verified sources that bars or limits a health plan's repayment claim against a crash settlement. So read the plan documents for a reimbursement or subrogation clause. Then ask the plan for its claim in writing. Medicare follows federal rules. What the District's lawyer ethics rules do settle is handling: under D.C. Rule of Professional Conduct 1.15(d), a disputed portion of settlement money stays separate until resolved, and the undisputed portion is paid to you. Our D.C. settlement check page explains the timing.
Yes. A PIP claimant whose condition matters must attend exams under the policy, and you can get a free copy of each report.
Under D.C. Code section 31-2411(b), a person claiming PIP whose condition is at issue must attend exams by physicians as the policy provides. On request, you get a free copy of every written report. The insurer may ask for the names of every provider who treated you for the injury and any relevant past injury, and for authorization to copy those records. Payment rules matter too. Under 31-2410(c), PIP is overdue if not paid within 30 days after reasonable proof of loss, and interest runs. A lawsuit for PIP benefits must be filed within three years under 31-2411(a).
Use your health card for care, check whether you bought PIP, decide on the PIP election within 60 days, and keep every bill and letter.
What a case like this is worth: value turns on the injury, treatment, lost income, fault, the PIP election and the insurance limits. See how D.C. settlements are valued.
Top USA Law's Washington, D.C. office is at 700 12th St NW, Suite 700. Andranik "Andy" Boyadzhyan, Attorney at Law, licensed in Washington, D.C., wrote this page. We meet clients by phone, by video or in person, and you pay no fee unless we win, and costs may apply. See the Washington, D.C. car accident lawyer page and the D.C. car accident attorney overview.
Related Washington, D.C. questions: chiropractic care, rental cars, what a lawyer costs.
Time away from work follows its own PIP formula, explained in how lost wages work after a District crash.
Sue within three years, or two after a death. District claims need Mayor notice in six months; elect PIP in 60 days.
A licensed Washington, D.C. attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Washington, D.C. claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.