


Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety
Serving Washington, D.C.
Hurt in a crash? The insurance company already has a team working on your claim. You should too. A free call tells you where you stand.
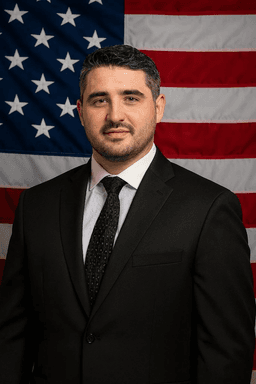 Your attorneyAndranik "Andy" Boyadzhyan, Esq.Founding Attorney. Licensed in Washington, D.C.
Attorney advertising. Services are not available in all states.
By Andranik "Andy" Boyadzhyan, Attorney at Law. Meet the team
In Washington, D.C., when your car is totaled the insurer must pay what it was actually worth the moment before the crash, based on cars of the same make, model and year in your area. The at-fault driver's insurer or your collision coverage pays. Top USA Law can review the offer and any injury claim for free.
Key takeaways
The insurer owes what your car was actually worth the moment before the crash. It can then take the title when it pays the claim.
The District's insurance regulator, the Department of Insurance, Securities and Banking (DISB), explains the rule in its consumer guidance. When the claims adjuster decides the cost to repair your car is greater than its value, the insurer may declare it a total loss. The company must pay what your vehicle was actually worth at the moment before the crash, and it has the option to take the title when it issues payment.
That measure is known as actual cash value. It is not what you paid, not what you owe on the loan, and not the cost of a new car. For a car that was damaged on the Southeast Freeway or crushed in a chain crash on I-295, the question becomes what a comparable car was worth in the D.C. area just before the crash.
DISB says insurers use a pricing guide and check what the same make, model and year is worth in your area. You should check too.
According to DISB, the insurer will use a recognized pricing guide to value the car, and the adjuster will check what a car like yours, the same make, model and year, is worth in your general area. DISB also tells consumers it is a good idea to research the value independently before agreeing to a settlement. Condition, mileage, options and recent work all move the number.
| Item | What to check | What helps |
|---|---|---|
| Comparable cars | Same make, model, year and trim, in the D.C. area | Dealer listings with mileage and options |
| Mileage | The odometer reading the insurer used | A recent service record or inspection |
| Options and packages | Every option is counted | The window sticker or build sheet |
| Condition | Any "poor condition" deduction | Photos taken before the crash |
| Recent work | New tires, brakes or major repairs | Receipts |
| Prior damage | Any deduction for old damage | Repair records showing it was fixed |
District law has a separate test for the title. Under D.C. Code section 50-1331.01, a salvage vehicle is one damaged so that the cost to rebuild it to its pre-damage condition is more than 75 percent of its retail value before the damage, as shown in an approved national pricing compilation. That definition controls title branding at the DMV; it does not set what the insurer pays.
Top USA Law. Services are not available in all states.
Fill in four quick fields, and a licensed attorney reviews the facts of your case at no cost.
If the other driver caused the crash, that driver's insurer pays. You can also claim under your own collision coverage, less your deductible.
| Situation | Who pays | Watch for |
|---|---|---|
| Other driver at fault and insured | That driver's property damage liability coverage | Contributory negligence defense; the policy limit |
| You carry collision coverage | Your insurer, less your deductible | Your insurer can seek repayment from the at-fault side |
| Other driver uninsured | Your collision coverage, or uninsured motorist property damage | A deductible applies |
| Hit and run | Your collision coverage or uninsured motorist coverage | Report to police and your insurer promptly |
| Flood, fire, theft or a falling tree | Your comprehensive coverage | Your deductible |
District policies must carry property damage liability of at least ten thousand dollars under D.C. Code section 31-2406, and uninsured motorist property damage of at least five thousand dollars with a two hundred dollar deductible. When the car was worth more than the at-fault driver's limit, your own collision coverage may close the gap. Under District of Columbia common law, contributory negligence applies to a claim for the car just as it does to an injury claim, so a driver found even slightly at fault may recover nothing from the other driver. See being partly at fault in D.C., and for the required coverages, our D.C. insurance minimums page.
The car is often the first check, not the last. If you were hurt, the worksheet for a D.C. injury claim lists the losses that sit outside the property claim. How long a car accident case takes in the District explains the stages of the injury side. The D.C. crash checklist covers the records to keep for both.
Ask for the valuation report in writing and answer it with your own comparable cars and records. If the insurer stalls, complain to DISB.
Under D.C. Code section 31-2231.17, it is an unfair claim settlement practice, when an insurer does it as a general business practice, to refuse to pay without a reasonable investigation, to fail to act reasonably promptly on claim communications, or to fail to give a reasonable and accurate explanation of a compromise offer. DISB enforces that section and takes complaints at disbcomplaints@dc.gov, according to its guidance. Your own policy may also have an appraisal clause for disputes over value. Read whether to accept the first offer in D.C. before signing.
The insurer pays the car's value, not your loan balance. The difference stays your debt unless you bought gap coverage.
When you finance or lease, the payment can go to the lender first, and any amount above the payoff comes to you. If the loan balance is higher than the car's actual value, you still owe the lender the rest. Gap coverage, sold with some loans and leases or as a policy add-on, can pay that difference, subject to its terms. Find your loan or lease papers before you talk numbers with the adjuster.
A rental is part of the claim against the at-fault driver, but DISB says insurers need not pay one once the car is totaled.
DISB's guidance says the other driver's insurer should pay rental costs for a reasonable length of repair time when your car was damaged by that driver's negligence. If your car is totaled, DISB says many companies pay for a rental as a courtesy, but they are not required to. Under your own policy, a rental is covered only if you bought rental reimbursement coverage, which has a dollar limit. Ask in writing how long the rental will last.
The rental car guide for District drivers goes deeper on replacement transportation, and timing of a District settlement check explains when injury money arrives if you were also hurt.
The injury claim is separate from the car claim. Sign no release that covers more than property damage, and watch the 60 day PIP clock.
A crash that totals a car can injure the people inside it. If you bought PIP, it can pay medical bills regardless of fault, but you must elect it within 60 days under D.C. Code section 31-2405, and electing limits a later lawsuit. Make sure any check or release for the car says it is for property damage only. Our pages on the D.C. no-fault option and chiropractic care after a D.C. crash explain the medical side.
What a case like this is worth: the car's value is one piece; injuries, lost work and policy limits drive the rest. Read how D.C. settlements are valued.
You have three years to sue over the car or an injury. Notice to the Mayor on a District claim is due within six months.
Under D.C. Code section 12-301(3), an action for damage to personal property, such as your car, must be brought within three years. An injury lawsuit has the same three years under 12-301. If a District government vehicle hit you, written notice to the Mayor is due within six months under D.C. Code section 12-309. Get the police crash report early; our D.C. crash report guide shows how.
Top USA Law's Washington, D.C. office is at 700 12th St NW, Suite 700. Andranik "Andy" Boyadzhyan, Attorney at Law, licensed in Washington, D.C., wrote this page. You pay no fee unless we win, and costs may apply. See our Washington, D.C. car accident lawyer page.
Related Washington, D.C. questions: rear-end collision claims, T-bone accident fault, uninsured drivers.
If a commercial truck totaled your car on New York Avenue or I-395, the Washington, D.C. truck crash lawyer page covers the carrier claim, and the Washington, D.C. car accident lawyer page covers the injury rules.
Sue within three years, or two after a death. District claims need Mayor notice in six months; elect PIP in 60 days.
A licensed Washington, D.C. attorney, Andranik "Andy" Boyadzhyan, Founding Attorney, reviews every Washington, D.C. claim, and our team helps you in English or Spanish.
Andranik "Andy" Boyadzhyan, Esq.
Founding Attorney
Licensed in Alabama, Missouri, New Mexico and Washington, D.C.
Featured in CNN, Forbes, Variety

Paul Perkins, Esq.
Of Counsel
Licensed in New Jersey and New York
Certified by the New Jersey Supreme Court as a Civil Trial Attorney. Lawyer of Distinction in Civil Litigation.
Featured in CNBC, Bloomberg, Forbes, The New York Times
Andranik "Andy" Boyadzhyan is the founding attorney of Top USA Law. His background spans business law, civil litigation, and personal injury, and his practice today focuses on motor vehicle accident claims.
Sundas Shafi, Esq., Attorney at Law, Head of Litigation
Rosette Kalayjian, Attorney at Law
Sandra Alves, Case Manager
Four steps from your first call to the close of your claim. You focus on healing while we deal with the insurers and keep you updated.
Free consultation
Call 24/7 or send the short form. An attorney reviews what happened and tells you where you stand. Free, no obligation.
We deal with the insurers
We deal with the insurance companies, request the police report and medical records, and keep you updated.
We build your case
Evidence, witnesses, experts and the medical picture of your injuries, prepared as if the case will go to trial.
You get paid
Medical bills, lost wages, vehicle damage, and pain and suffering. No fee unless we win; costs may apply.
Reviewed by Andranik "Andy" Boyadzhyan, Esq.
Fill in the four short fields in this form, and a licensed attorney reviews your case for free. We respond day or night.
Top USA Law. Services are not available in all states.
Takes 30 seconds. No obligation.